All Categories
Featured
There's no warranty that you'll certify to file, but declaring Chapter 7 personal bankruptcy could result in having your debts canceled, and a Chapter 13 insolvency could get you into a 3-5 year payment strategy to eliminate financial obligation. Here's what you need to consider first:. Some debtors have no viable way to pay back all of their debt.
When you apply for bankruptcy, the court issues an automated stay, suggesting that financial institutions will be barred from making collection efforts on your debts through phone calls and letters. As soon as you file, creditors will deal solely with your lawyer and not you. When you declare bankruptcy your lenders need to stop all foreclosure and foreclosure procedures.
Personal bankruptcy is among the most damaging occasions for your credit, and it remains on your credit reports for 7-10 years after you submit. This could indicate being rejected new loans and credit in the near future. You'll need to spend for a lawyer, plus court filing costs, paralegal costs, insolvency trustee costs and fees for the required consumer therapy.
Does Your Debt Match 2026 Market Realities?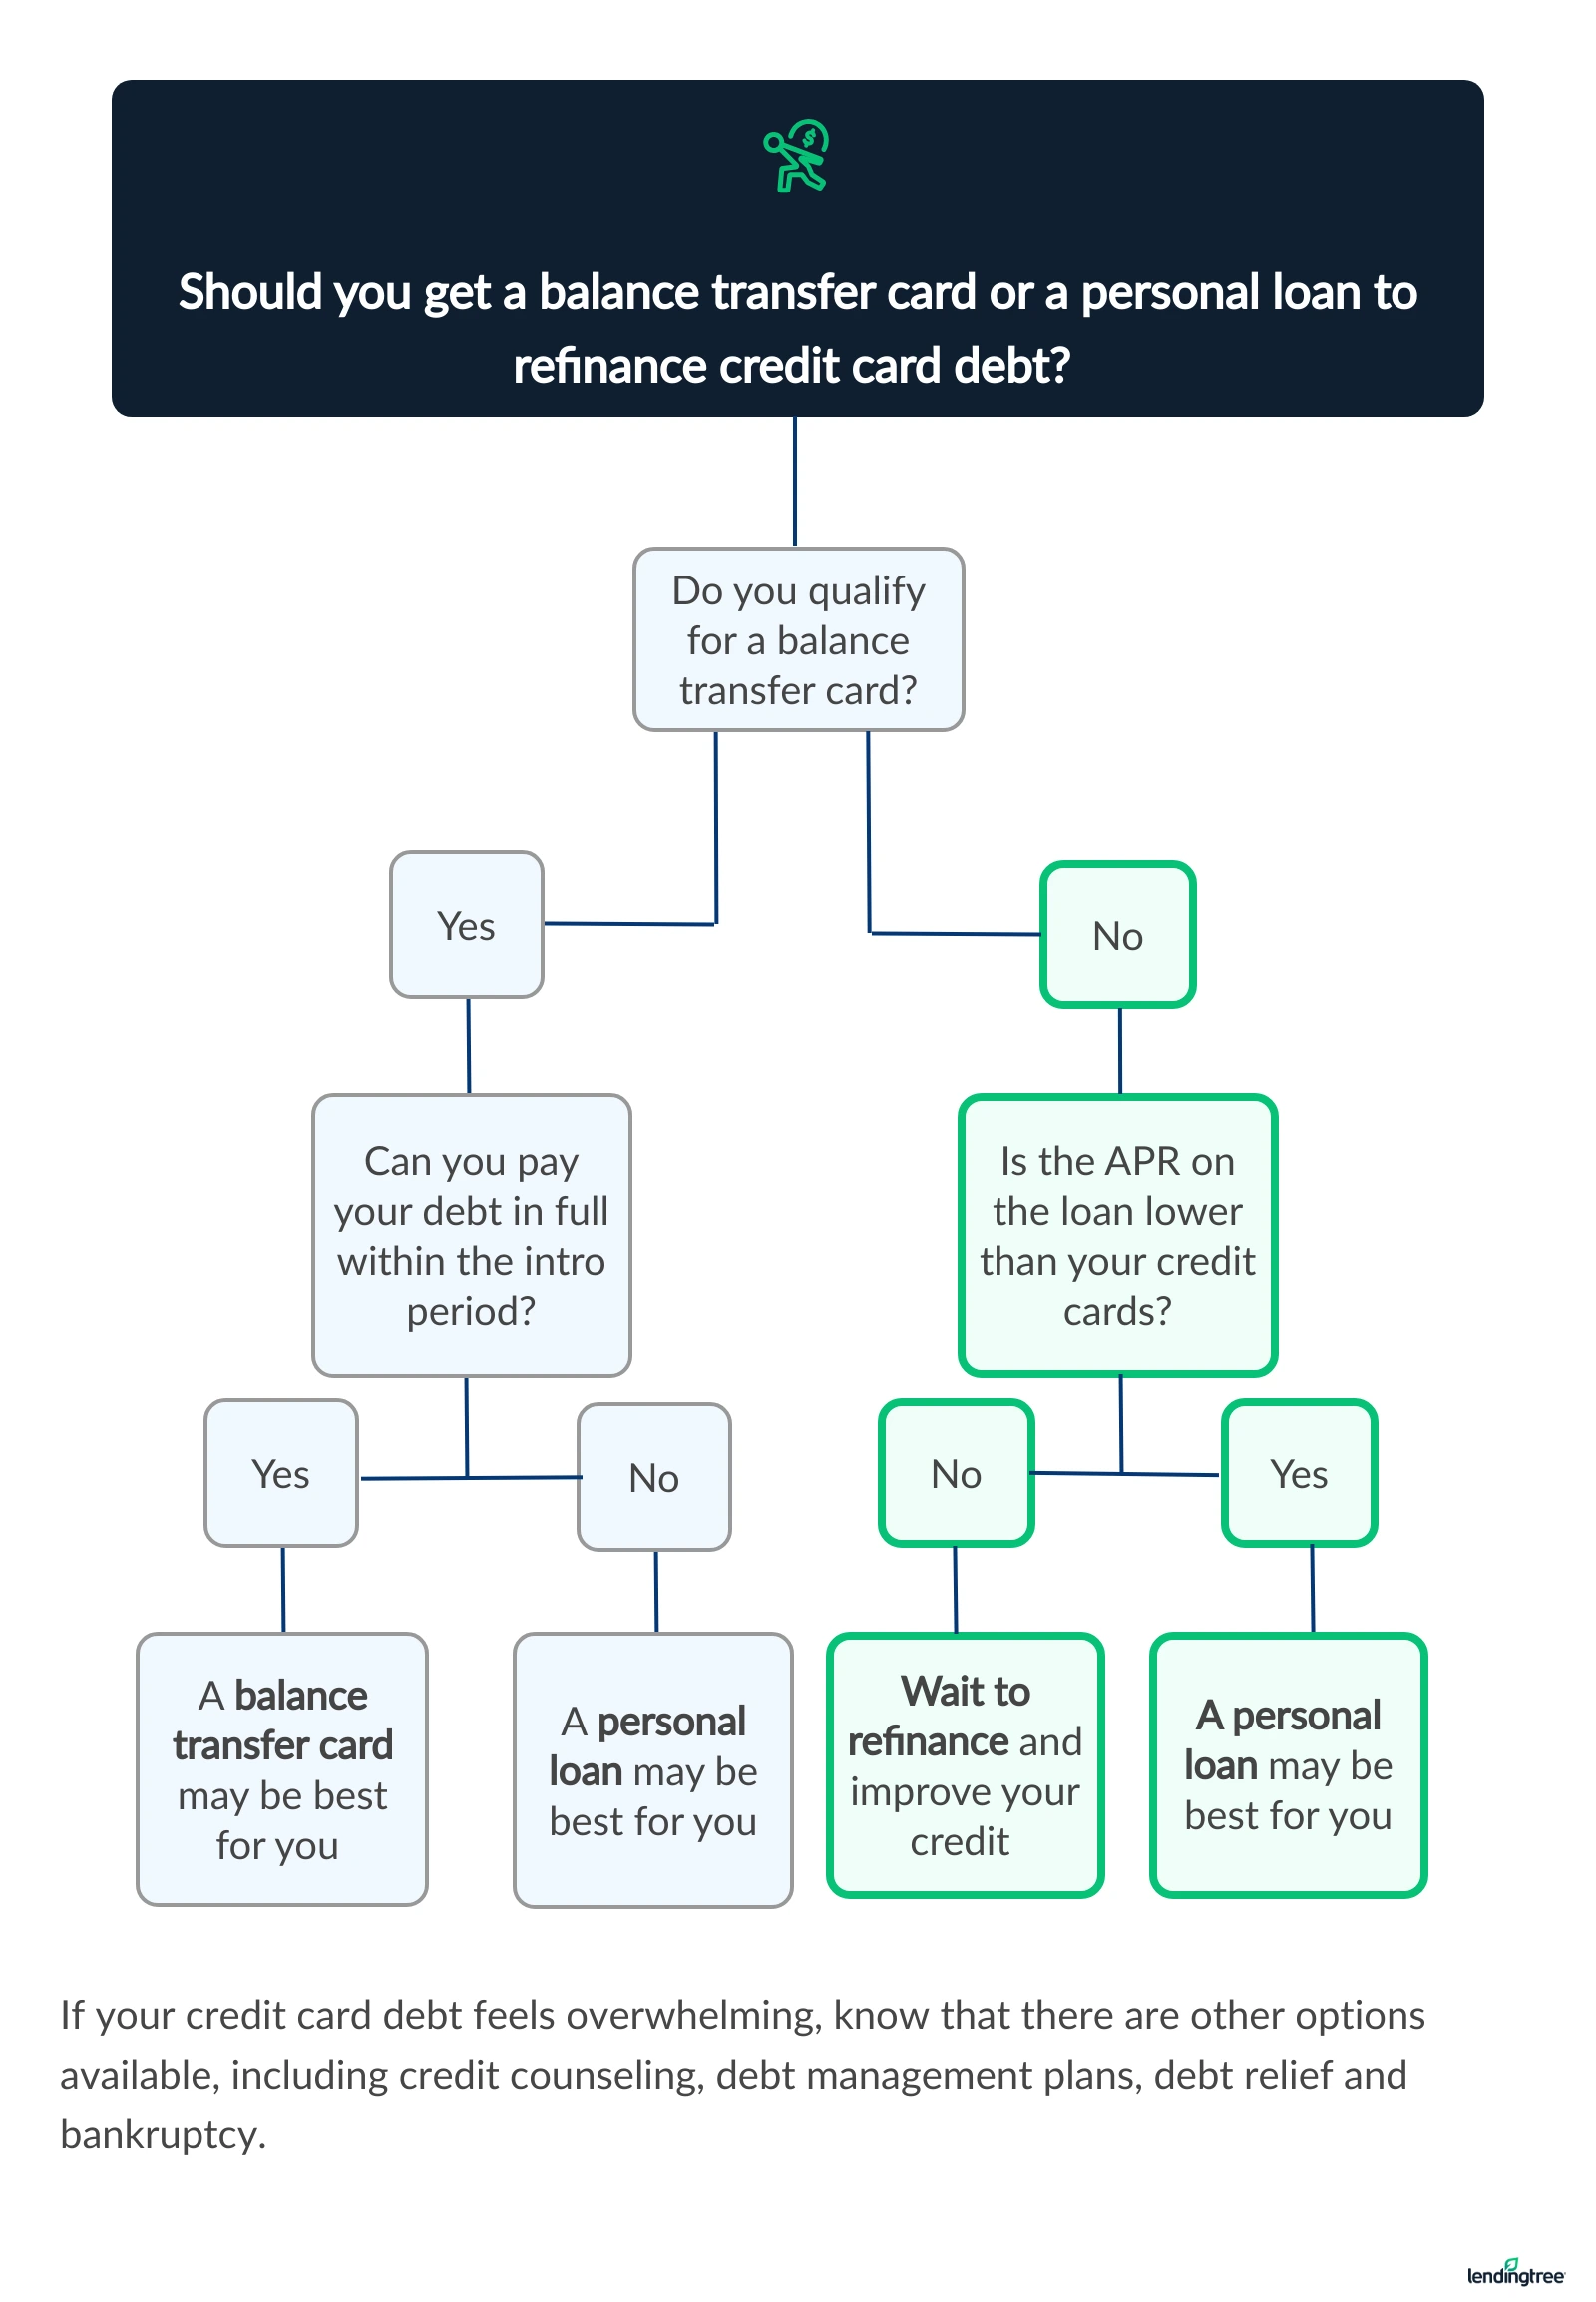
You do not need to deal with a third-party to get debt-relief. Some options for reducing debt could save you money and help maintain your credit The best solution for you might even include a combination of DIY options, spending plan tools or financing options. Here are a few of the things you can do on your own: Are you clear on where all your cash is going? If you don't keep track, there are probably a lots of costs you don't recognize are setting you back.

Latest Posts
Why to Find 2026 Financial Relief Help Immediately
Successful Ways to Lower Interest Rates
Evaluating the Top 2026 Credit Relief Options